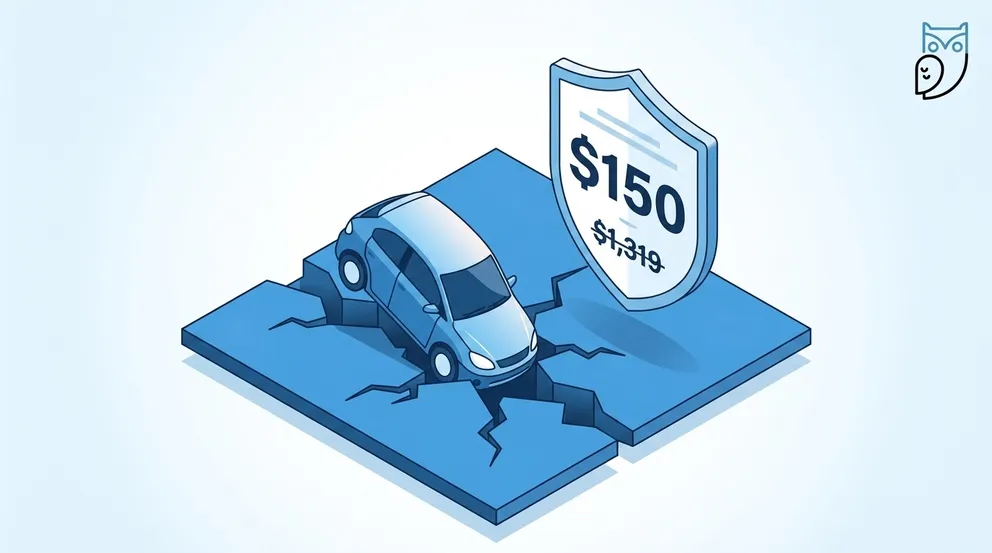
Comprehensive coverage pays for earthquake damage to your car, and no other part of an auto policy does. Liability and collision both exclude it. Comprehensive averaged $238.21 per insured vehicle in 2023 according to the NAIC, and California drivers pay only $150.05 a year for it.
Roughly 75% of the United States could experience damaging earthquake shaking, according to the 2023 National Seismic Hazard Model built by a USGS-led team of more than 50 scientists and engineers. California carries a 95% or greater probability of damaging shaking within the next century. Yet only 12.48% of California residential insurance policies carried earthquake coverage in 2024, per the state Department of Insurance.
Car owners are in a very different position. Earthquake protection for a vehicle comes bundled inside standard comprehensive coverage at no separate charge, with a flat deductible instead of the 5% to 25% percentage deductible the California Earthquake Authority applies to homes.
- Only comprehensive coverage pays for quake damage, and about 80% of insured US drivers carry it, per Triple-I analysis of NAIC data.
- California charges $150.05 a year for comprehensive, the third-cheapest rate among 51 US jurisdictions, despite sitting in the highest seismic hazard zone in the country.
- Earthquake coverage on a California home averaged $1,319.07 per homeowners policy in 2024, roughly 8.8 times what auto comprehensive costs in the same state.
- Fire, landslide, tsunami, and falling debris triggered by a quake all fall under the same comprehensive claim.
- Insurers impose binding moratoriums after a quake, so shopping for comprehensive during the aftershock window will not work.
Which Coverage Pays After an Earthquake
An auto policy is three separate products sold together, and a quake triggers exactly one of them. Comprehensive handles losses that happen without a collision: theft, hail, fire, falling objects, and seismic events. Collision only responds when your vehicle strikes something or something strikes it in a traffic accident. Liability pays other people, never you.
| Coverage | Pays for Earthquake Damage? | 2023 Average Annual Premium (NAIC) | What It Actually Does |
|---|---|---|---|
| Comprehensive | Yes | $238.21 | Non-collision losses including quake, fire, theft, and falling debris |
| Collision | No | $463.69 | Impact with another vehicle or object while driving |
| Liability | No | $737.00 | Injury and property damage you cause to other people |
Source: NAIC 2023 Auto Insurance Database Average Premium Supplement, published June 2025. Figures are countrywide written premium divided by written car-years and reflect all deductible levels and limits combined.
That structure catches people off guard. If you carry state-minimum liability in Nevada or Utah, an earthquake that drops a carport onto your hood leaves you paying the entire repair bill yourself. The distinction between the two physical damage coverages is worth understanding before a disaster, and our breakdown of comprehensive versus collision coverage walks through where each one applies.
No US insurer sells a standalone earthquake policy for a personal vehicle. Comprehensive is the only route, which means the 20% of insured drivers without it have zero seismic protection regardless of what they pay for liability.
What Comprehensive Pays For After a Quake
Direct ground shaking rarely destroys a parked car by itself. Nearly all quake-related vehicle losses come from what the shaking knocks loose, and comprehensive treats those secondary events as part of the same covered peril.
- Falling masonry, signage, or facade material striking a parked vehicle
- Garage and parking-structure collapse, including pancaked multi-level decks
- Fire following a quake, which caused most of the destruction in the 1906 San Francisco event and remains the largest secondary risk today
- Landslide, mudslide, and rockfall along hillside roads
- Trees and utility poles brought down by ground movement
- Tsunami inundation and flooding from ruptured water mains
- Road buckling or sinkhole formation that swallows or grounds a vehicle
Ruptured gas lines make fire the most expensive of these. The 1994 Northridge earthquake produced $15.3 billion in insured losses, equal to $32.2 billion in 2023 dollars, according to the Insurance Information Institute. FEMA's 2017 study put average annual US earthquake losses at $6.14 billion across all property types.
What Your Auto Policy Will Not Cover
Five gaps trip up claimants after a seismic event:
- Personal belongings inside the car. A laptop crushed in the trunk falls under homeowners or renters insurance, not auto.
- Your deductible always comes off the top, typically $500 or $1,000 for comprehensive.
- Diminished value, meaning the resale hit a repaired car carries, is not reimbursed in most states.
- Custom wheels, lift kits, and aftermarket stereo equipment need a separate endorsement before the loss occurs.
- Rental cars and rideshares while your vehicle sits in the shop require rental reimbursement coverage, which is a separate line item.
Most carriers impose a binding moratorium after a significant quake, freezing new policies and coverage increases until aftershock risk drops. The USGS put the chance of a magnitude 3 or higher aftershock at 56% within one week of the April 2, 2026 magnitude 4.6 Boulder Creek quake near Santa Cruz. Adding comprehensive during that window is generally impossible.
Comprehensive Coverage Cost in High-Risk Earthquake States
The USGS identifies 16 states with the highest earthquake hazard, and 37 states have recorded a magnitude 5 or larger event in the past 200 years. Pricing in those 16 states does not track seismic risk at all. Hawaii, Nevada, California, and Washington happen to be the four cheapest comprehensive markets in the country.
| State | 2023 Comprehensive Premium | Monthly | Change vs. 2022 | vs. National ($238.21) | Cheapest Rank (of 51) |
|---|---|---|---|---|---|
| Hawaii | $117.23 | $9.77 | +6.9% | -50.8% | #1 |
| Nevada | $135.87 | $11.32 | +11.7% | -43.0% | #2 |
| California | $150.05 | $12.50 | +43.9% | -37.0% | #3 |
| Washington | $153.93 | $12.83 | +18.6% | -35.4% | #4 |
| Utah | $160.02 | $13.34 | +15.1% | -32.8% | #6 |
| Oregon | $165.24 | $13.77 | +31.5% | -30.6% | #8 |
| Idaho | $174.89 | $14.57 | +11.1% | -26.6% | #10 |
| Alaska | $180.15 | $15.01 | +11.8% | -24.4% | #12 |
| Kentucky | $218.00 | $18.17 | +19.3% | -8.5% | #21 |
| Illinois | $218.74 | $18.23 | +27.5% | -8.2% | #22 |
| Tennessee | $229.21 | $19.10 | +18.8% | -3.8% | #25 |
| South Carolina | $250.78 | $20.90 | +11.2% | +5.3% | #32 |
| Arkansas | $291.66 | $24.31 | +12.4% | +22.4% | #36 |
| Missouri | $307.96 | $25.66 | +21.4% | +29.3% | #38 |
| Montana | $365.45 | $30.45 | +9.5% | +53.4% | #47 |
| Wyoming | $452.42 | $37.70 | +14.3% | +89.9% | #50 |
Source: NAIC 2023 Auto Insurance Database Average Premium Supplement (Table 3C), published June 2025. High-hazard state list from USGS seismic hazard mapping as summarized by the Insurance Information Institute. Rank compares all 50 states plus the District of Columbia, cheapest to most expensive. Comprehensive average premium equals comprehensive written premiums divided by comprehensive written car-years.
Hail, not earthquakes, drives the expensive end of that table. Wyoming at $452.42 and Montana at $365.45 price comprehensive high because Great Plains hailstorms total roofs and vehicles every summer. Seismic exposure barely registers in comprehensive rating, which is why a Californian buys quake protection for $12.50 a month while a Wyoming driver pays triple that for hail protection.
California's 43.9% single-year jump from $104.30 to $150.05 came from post-wildfire rate filings approved after years of suppressed pricing, not from earthquake losses. Drivers tracking those increases can compare current pricing on our California car insurance rates page.
Car Earthquake Coverage Costs 89% Less Than Home Coverage
California's 2024 earthquake data call gives the cleanest available comparison between protecting a house and protecting the car parked next to it. The gap is enormous, and it runs in the direction most people would not guess.
| Factor | Vehicle (Comprehensive) | Home (Earthquake Endorsement) | Difference |
|---|---|---|---|
| Average annual premium in CA | $150.05 | $1,319.07 | Auto costs 88.6% less |
| Deductible structure | Flat $500 or $1,000 | 5% to 25% of dwelling limit | $75,000 on a $500K home at 15% |
| How you buy it | Included in comprehensive, no endorsement | Separate CEA or private policy | Auto requires no extra purchase |
| Take-up rate | About 80% of insured drivers nationally | 14.94% of CA homeowners policies | 5.4x higher adoption |
Sources: California Department of Insurance Earthquake Premium and Policy Count Data Call, 2024 experience year (1,609,655 earthquake policies across 12,897,508 residential policies statewide). Auto figures from NAIC 2023 supplement and Triple-I analysis of NAIC data. Deductible ranges from the California Earthquake Authority homeowners policy schedule.
Run the deductible math on a real loss. A quake drops a section of parking garage onto a 2022 Toyota RAV4 and the estimate comes to $9,400. With a $1,000 comprehensive deductible, your insurer sends $8,400 and you cover $1,000. The homeowner next door with a $500,000 dwelling limit and a 15% CEA deductible absorbs $75,000 of foundation repair before any check arrives. Picking the right number matters, and our guide to choosing a car insurance deductible shows how each step changes your premium.
A California driver buys earthquake protection for a $35,000 vehicle for $12.50 a month. The same driver would pay $109.92 a month to protect the house, and would still owe the first $75,000 of any claim.
How Earthquake Claims Get Settled
Comprehensive pays actual cash value, meaning the pre-quake market value of your vehicle minus depreciation, capped at that figure rather than what a replacement costs today. Insurers declare a total loss when repair estimates cross a state threshold, generally 70% to 80% of ACV. Total losses now account for a record 23.1% of all auto claims as repair costs climb, so a moderately damaged car crosses that line faster than it did five years ago.
Average comprehensive claim severity reached $2,738 in 2022, up from $2,042 in 2021, per Triple-I analysis of NAIC data. Only 3.3% of policyholders filed a comprehensive claim that year. Should your car total out, the settlement math is negotiable, and drivers who push back on lowball valuations recover more, as our walkthrough on negotiating a total loss settlement explains.
Financed and leased vehicles create the ugliest scenario. If a quake totals a car worth $20,000 while you owe $25,000, the insurer pays $20,000 minus your deductible and the lender still wants the remaining $5,000. Only gap insurance closes that shortfall.
Filing an Earthquake Damage Claim
Photograph everything before moving the vehicle
Capture the debris, the collapsed structure, and the surrounding scene from four angles. Adjusters need proof the damage traces to seismic activity rather than a prior fender bender.
Record the USGS event details
Note the magnitude, epicenter, and timestamp from earthquake.usgs.gov. Attaching the official event ID to your claim file removes any dispute about the date of loss.
Call your insurer within 24 to 72 hours
Most policies require prompt notice, and carriers deploy catastrophe adjusters to quake zones within days. Filing early puts you ahead of the backlog that follows any magnitude 6 or larger event.
Compare the repair estimate against your deductible
A $1,400 windshield and hood repair against a $1,000 deductible nets you $400, which rarely justifies a claim on your record. Damage above $2,500 almost always does.
Request the valuation report if the car totals
Insurers must show the comparable vehicles used to set your ACV. Challenge any comparable with higher mileage or a lower trim level than your car.
Is Comprehensive Worth It for Earthquake Risk
Earthquake exposure alone does not justify comprehensive on a beater. Standard guidance says drop physical damage coverage once the annual premium plus deductible exceeds 10% of the car's value, and at $150.05 in California a vehicle worth under $6,500 sits near that line. Our analysis of when to drop collision and comprehensive runs the numbers by vehicle age.
- Your car is worth more than $8,000 or carries a loan or lease
- You park in a multi-level structure, under a carport, or on a hillside street
- Hail, theft, deer strikes, or wildfire smoke are realistic threats where you live
- The premium runs under $200 a year, which describes 12 of the 16 highest-hazard states
- Your vehicle books below $4,000 and the loan is paid off
- Garage parking in a single-story structure removes most falling-debris exposure
- You have enough savings to replace the car outright without financing
- Wyoming and Montana pricing above $365 a year erodes the value on a low-book vehicle
Comprehensive earns its keep on frequency, not on the rare catastrophe. Windshield chips, parking lot theft, and hail dents all fall under the same $150 to $238 premium, which is why glass claims outnumber quake claims by orders of magnitude. Earthquake protection is the bonus that comes attached. If you are still deciding between coverage tiers, our comparison of liability-only versus full coverage lays out the tradeoff by driver profile.
Add comprehensive during a calm stretch, not after the news reports a quake. Carriers in Washington and Oregon commonly hold moratoriums for 48 to 72 hours after a felt event, and California insurers extend them until aftershock probability drops below their threshold. Coverage bought today protects you from a quake tomorrow.
Frequently Asked Questions
Yes, comprehensive coverage pays for earthquake damage to your vehicle, including damage from falling debris, garage collapse, landslides, and fire that follows a quake. Liability and collision coverage both exclude seismic events. Comprehensive averaged $238.21 per insured vehicle nationally in 2023 according to NAIC data, and about 80% of insured US drivers carry it.
No. Unlike homes, which require a separate California Earthquake Authority policy or private endorsement, vehicles get earthquake protection automatically inside standard comprehensive coverage at no additional charge. There is no standalone earthquake policy sold for personal vehicles in the United States.
Your standard comprehensive deductible applies, typically $500 or $1,000. That is a flat dollar amount, unlike home earthquake coverage where the California Earthquake Authority applies a percentage deductible of 5% to 25% of the dwelling limit, meaning $75,000 out of pocket on a $500,000 home at a 15% deductible.
Usually not. Most insurers impose a binding moratorium after a significant quake that blocks new policies and coverage increases until aftershock risk subsides. The USGS estimated a 56% chance of a magnitude 3 or higher aftershock within a week of the April 2026 magnitude 4.6 Boulder Creek quake in California. Coverage must be in force before the event to respond to it.
Comprehensive claims are not-at-fault losses, so most carriers do not apply the surcharge that follows an at-fault accident. The claim does appear on your CLUE report for five to seven years, and filing multiple comprehensive claims can cost you a claims-free discount worth 10% to 20% at renewal.
No. Homeowners and renters policies exclude vehicles entirely, even a car parked inside your own garage when the structure collapses. Auto comprehensive is the only coverage that responds. Homeowners insurance does cover personal belongings that were inside the vehicle, subject to your home policy deductible.
- NAIC - 2023 Auto Insurance Database Average Premium Supplement (June 2025)
- USGS - New Map Shows Where Damaging Earthquakes Are Most Likely to Occur
- USGS - 2023 50-State Long-Term National Seismic Hazard Model
- California Department of Insurance - Earthquake Premium and Policy Count Data Call, 2024 Residential Totals
- Insurance Information Institute - Background on Earthquake Insurance and Risk
- Insurance Information Institute - Facts and Statistics: Auto Insurance
- California Earthquake Authority - Homeowners Earthquake Insurance Policies